Gold as Insurance: How Precious Metals Protect Your Wealth from Economic Uncertainty
Kelvin Bratton2026-09-20
Most people insure their homes, cars, and health. But what about your purchasing power?
When inflation surges, currencies lose value, or markets crash, traditional insurance policies won't protect the money sitting in your bank account. Gold and silver have served as financial insurance for thousands of years, not because they generate income, but because they preserve wealth when other assets fail. According to the World Gold Council, gold maintained its purchasing power over the past century while the U.S. dollar lost approximately 96% of its value.
This article explains how gold functions as economic insurance, when it performs best, and how to incorporate it into your wealth protection strategy.
Why Gold Works as Insurance Against Economic Risk
Insurance exists to protect against losses you can't afford to absorb. Fire insurance covers your house. Health insurance covers medical bills. Gold insurance covers something more fundamental: the erosion of your wealth's value.
Physical gold and silver are tangible assets with no counterparty risk. When you hold them outright, they don't depend on a government's promise, a bank's solvency, or a corporation's credit rating. This makes them different from bonds, stocks, or even cash. If a financial institution collapses, your gold doesn't disappear with it.
The metal's value stems from scarcity and universal recognition. Humans have prized gold for over 5,000 years across every major civilization. That track record matters when paper currencies come and go. According to a study by DollarDaze, 775 fiat currencies have failed throughout history, with an average lifespan of just 27 years.
Unlike insurance policies that pay premiums for protection you hope never to use, gold sits as a physical asset that typically appreciates during the exact moments when other holdings decline. During the 2008 financial crisis, the S&P 500 fell 38.5% while gold rose 5.5%. In 2020, when COVID-19 triggered market chaos, gold climbed 25% as stocks plunged.
The Four Economic Threats Gold Protects Against
Inflation and Currency Debasement
When governments print money to fund spending or stimulate economies, each dollar buys less. From 2020 to 2022, the U.S. money supply grew by roughly 40%, contributing to inflation rates not seen in four decades. During this period, consumer prices jumped more than 8% annually while wages struggled to keep pace.
Gold historically rises with inflation. An ounce of gold cost $35 in 1971 when President Nixon severed the dollar's link to gold. That same ounce trades above $2,000 today. Your great-grandparents could buy a quality suit for one ounce of gold in 1920. You can still buy a quality suit for one ounce today. The suit's dollar price changed, but gold's purchasing power didn't.
Central banks understand this relationship. They hold over 36,000 tonnes of gold in reserve, according to the World Gold Council. If gold were obsolete, why would monetary authorities stockpile it?
Banking System Failures
Banks operate on fractional reserve systems. They lend out most deposits and keep minimal cash on hand. During banking crises, depositors rush to withdraw funds simultaneously. The system can't handle it.
Cyprus learned this in 2013 when banks froze accounts and seized deposits to prevent collapse. Depositors with over €100,000 lost up to 60% of their savings. Physical gold in a home safe or secure depository doesn't face this risk. There's no bank that can freeze it, no institution that can confiscate it through a bail-in.
Liberty Gold Silver ships metals with full insurance through private carriers, not through vulnerable banking channels. Every shipment is tracked from vault to your door, with an adult signature required upon delivery. This ensures your insurance policy arrives intact.
Stock Market Crashes
Equities deliver strong long-term returns, but they crash violently during crises. The Dow Jones lost 89% during the Great Depression. Japan's Nikkei peaked in 1989 and didn't recover for three decades. Markets can stay irrational longer than you can stay solvent.
Gold provides portfolio ballast. Research by the University of Oxford found that a portfolio with 10% gold allocation reduced volatility while maintaining similar returns compared to a traditional 60/40 stock-bond mix. When stocks fell more than 5% in a single day between 1987 and 2015, gold rose on average.
This negative correlation makes gold effective portfolio insurance. You don't buy it hoping for crashes. You buy it knowing that when crashes come, your entire net worth won't sink together.
Geopolitical Instability
Wars, sanctions, and political upheaval make assets disappear. Property can be seized. Bank accounts frozen. Stock exchanges closed. Gold remains portable and universally accepted.
During World War II, refugees carried wealth across borders as gold coins sewn into clothing. When Venezuela's economy collapsed under socialism, citizens who owned gold preserved more wealth than those who trusted bolivars. Physical metals don't care about borders, governments, or political ideology.
How Much Gold Should You Hold as Insurance
Insurance coverage should match your risk tolerance and exposure. Most financial advisors who incorporate precious metals recommend 5-15% of a portfolio in gold and silver.
If you're protecting $500,000 in assets, that's $25,000 to $75,000 in physical metals. This provides meaningful insurance without over-concentrating in a single asset class. You're not betting on gold skyrocketing. You're hedging against scenarios where other holdings fail.
The allocation depends on several factors. Younger investors with decades until retirement can accept more volatility and might allocate toward the lower end. Those approaching retirement or already living off savings often allocate more, sometimes 20-25%, because they can't recover from major losses.
Your economic exposure matters too. If most wealth sits in real estate and stocks, gold diversifies away from those risks. If you hold significant cash or bonds, gold protects against inflation eroding fixed-income returns.
Physical Gold vs. Paper Gold: Real Insurance Requires Real Metal
Many investors buy gold ETFs, mining stocks, or futures contracts thinking they own gold insurance. They don't. These are paper claims on gold, not the metal itself.
Gold ETFs like GLD hold physical gold in vaults but introduce counterparty risk. You own shares in a fund, not bars. During a crisis severe enough to need your insurance, will the fund function properly? Will you be able to redeem shares for physical metal? The prospectus explicitly states you can't take delivery under most circumstances.
Mining stocks correlate more with equities than gold prices. When markets crash, mining shares often fall even as gold rises. Futures contracts expire and require rolling positions, creating tracking errors and costs.
Gold IRAs: Tax-Advantaged Insurance
Traditional IRAs and 401(k)s hold paper assets, stocks, and bonds. But IRS regulations allow Self-Directed IRAs to hold physical gold, silver, platinum, and palladium meeting minimum purity standards.
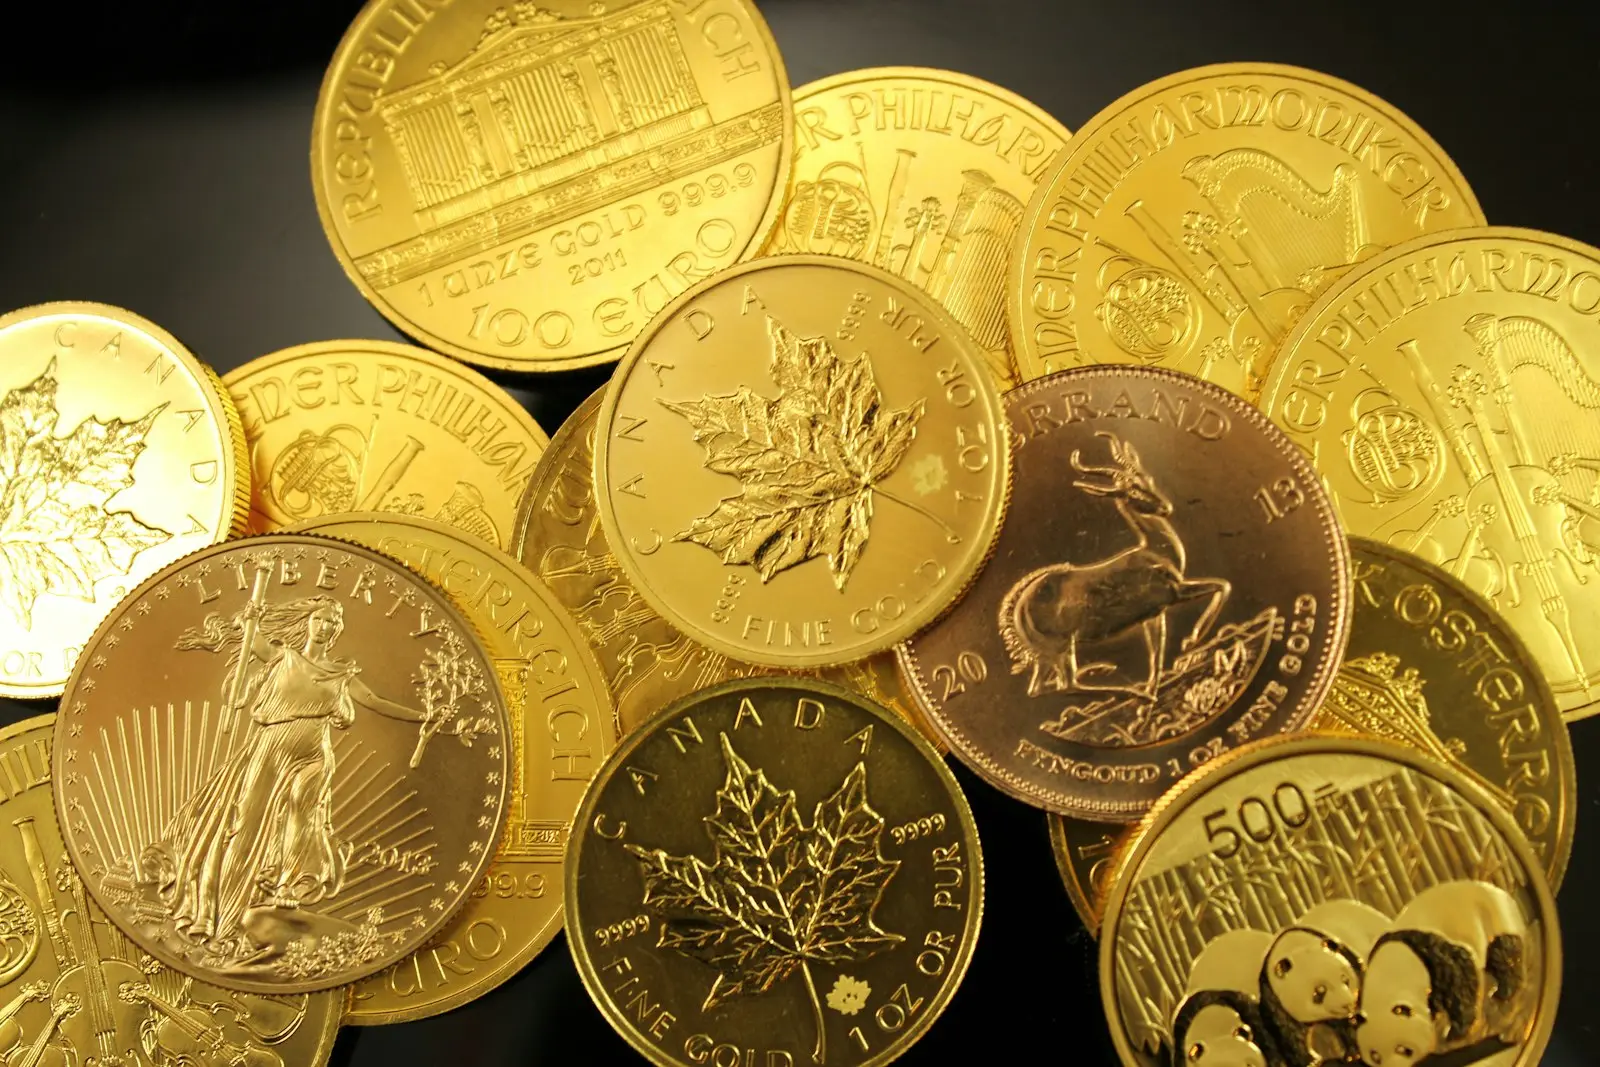
For gold, that's .995+ fine. For silver, .999+ fine. American Gold Eagles, Canadian Maple Leafs, and certain bars qualify. Collectible coins and jewelry don't.
A Gold IRA lets you shield wealth from economic risk while maintaining tax advantages. Contributions may be tax-deductible. Growth is tax-deferred. You're building retirement security with an asset uncorrelated to stocks and bonds filling most retirement accounts.
The mechanics are straightforward. You establish a Self-Directed IRA with an approved custodian. You can roll over existing IRA or 401(k) funds without tax penalties. The custodian purchases IRS-approved metals on your behalf and stores them in an approved depository. You maintain complete ownership, but the depository handles secure storage to meet IRS requirements.
Liberty Gold Silver coordinates directly with IRA custodians, simplifying the rollover process. The metals ship from trusted mints to approved depositories with full insurance coverage throughout. There are no games with authenticity. Everything is mint-sourced and verified.
Storage Considerations: Where Insurance Lives
Physical insurance needs secure storage. You have three main options.
Home Storage: Complete control and immediate access. No storage fees. But home safes offer limited security against determined thieves or disasters. Homeowner's insurance typically caps precious metals coverage at $1,000-$2,000 unless you purchase additional riders. For IRA metals, home storage violates IRS rules and triggers taxes plus penalties.
Bank Safe Deposit Boxes: Better security than most homes. Low annual cost, usually $50-$200 depending on box size. However, banks limit access to business hours. During banking crises, they can restrict or deny access. Contents aren't insured by the bank or FDIC. You'll need separate insurance. Banks also report safe deposit box rentals, creating a paper trail.
Bonded Depositories: Professional facilities designed specifically for precious metals storage. These offer the highest security with 24/7 monitoring, insurance up to full value, and regular audits. Storage fees typically run 0.5-1% of holdings annually. For IRA metals, this is the only compliant option.
Liberty Gold Silver works with Brink's and Delaware Depository, two of the industry's most established facilities. Your metals are held in allocated, segregated storage. That means specific bars and coins with serial numbers assigned to your account. Not pooled with other clients' holdings.
Liquidity: Insurance You Can Actually Use
Insurance only works if you can access it when needed. This makes liquidity critical. Gold and silver are among the world's most liquid assets.
This matters during emergencies. If unexpected medical bills arise or you need cash quickly during market turmoil, your gold insurance converts to currency on your timeline.
Gold vs. Silver: Choosing Your Insurance Coverage
Both metals serve as insurance, but they function differently.
Gold is dense value. A $50,000 position fits in a container the size of a coffee mug. It's easier to store, transport, and secure. Gold is also more stable, with lower volatility than silver. For pure wealth preservation, gold is typically the foundation.
Silver offers more upside potential but with greater volatility. Industrial demand accounts for roughly 50% of silver consumption, compared to 10% for gold. This means silver prices respond to both economic fears and industrial growth. During the 1970s inflation crisis, silver surged 2,200% while gold rose 1,500%.
Many investors split their insurance coverage, perhaps 70% gold and 30% silver. The gold provides stability and concentrated value. The silver adds leverage and remains affordable for smaller purchases. A balanced approach gives you options when it's time to sell. You can liquidate silver for small needs while leaving gold intact.
When Gold Insurance Doesn't Perform
Honesty requires acknowledging when insurance doesn't pay. Gold won't protect against every financial risk.
During strong economic expansions with low inflation, gold often stagnates or declines. From 1980 to 2000, gold fell from $850 to $280 per ounce. Stocks delivered extraordinary returns during this period. Investors who held only gold missed substantial gains.
Gold also pays no dividend or interest. A stock might generate 2% annual dividends. A bond pays coupon interest. Gold just sits there, maintaining value but not actively growing. In low-inflation environments, opportunity cost matters.
If deflation strikes, cash becomes king. Prices fall, so each dollar buys more. Gold typically holds value but doesn't outperform dollars gaining purchasing power. The Great Depression saw deflation, and gold's fixed price meant it didn't provide dramatic gains.
This is why gold is insurance, not speculation. You don't load 100% of assets into home insurance hoping your house burns down. You carry appropriate coverage against specific risks while pursuing growth elsewhere.
Building Your Economic Insurance Plan
Start by assessing what you're insuring. Calculate total net worth. Identify holdings most vulnerable to inflation, currency debasement, or market crashes. That's your exposure.
Decide on allocation. For most investors, 10% is a starting point. If you're younger with steady income, 5-10% might suffice. If you're retired, depending on savings, or concerned about near-term economic disruption, 15-20% provides more protection.
Choose between gold and silver based on storage capacity, budget, and risk tolerance. Many start with gold for core insurance, then add silver for diversification.
Determine storage method. Home storage works for modest amounts if security is adequate. For larger holdings or IRA metals, consider depositories. Liberty Gold Silver offers segregated storage through established facilities with complete insurance coverage.
Review annually. Like any insurance policy, your gold holdings should adjust as circumstances change. Significant wealth increases might require higher coverage. Moving from accumulation to retirement might shift allocation preferences. Rebalance as needed to maintain appropriate protection.
The Insurance Nobody Wants to Use but Everyone Needs
The best insurance policies never pay a claim. You insure your house hoping it doesn't burn. You buy life insurance hoping to die old. You hold gold hoping economic stability continues.
But hope isn't strategy. Since 1971, when fiat currency fully replaced gold backing, the U.S. has experienced eight recessions, multiple banking crises, double-digit inflation, massive currency debasement, and repeated stock market crashes. Each cycle, those holding physical precious metals preserved wealth while others watched savings evaporate.
Gold won't prevent crises. It won't stop inflation or reverse market crashes. But it will protect your purchasing power when paper assets fail. That's what insurance does. It transfers risk you can't afford to bear.
The question isn't whether economic disruption will occur again. History guarantees it will. The question is whether you'll be prepared when it does.
- World Gold Council. "Gold Investor: Risk Management and Capital Preservation." https://www.gold.org/
- DollarDaze. "History of Fiat Currency." http://dollardaze.org/
- University of Oxford. "Portfolio Diversification with Gold." Oxford Economics, 2020.
- U.S. Federal Reserve. "Money Supply Statistics." https://www.federalreserve.gov/
- Liberty Gold Silver. "Guide to Precious Metals." https://www.libertygoldsilver.com/learn/precious-metals
- Liberty Gold Silver. "IRS-Approved Precious Metals for IRAs." https://www.libertygoldsilver.com/precious-metals/ira-eligible
- Liberty Gold Silver. "Precious Metals Storage Options." https://www.libertygoldsilver.com/learn/storage
- Liberty Gold Silver. "Our Iron Pledges." https://www.libertygoldsilver.com/guarantee
This article is educational. It is not a recommendation to buy or sell anything, and it does not consider your circumstances. Prices can move in either direction.